Execution: market impact, implementation shortfall and capacity
SIG · Chapter 712 min readAsked at Two Sigma, Citadel, AQR, Point72
Assumes Portfolio construction: mean-variance, and why nobody uses it raw.
 1:01
The lesson in a minutePremium
The key idea, drawn and talked through in a short video before you read. Lesson videos come with Premium.
Start the 7-day free trialUnlockAfter this lesson you should be able to
- State the square-root impact law and what it implies for capacity.
- Decompose implementation shortfall into its parts.
- Describe the trade-off Almgren–Chriss formalises.
A signal that works on paper is worth nothing until it survives the cost of trading it. Impact grows with size, so every strategy has a capacity beyond which the edge is consumed – and finding that number is as much a part of research as finding the signal.
Equation 7.1
The square-root law
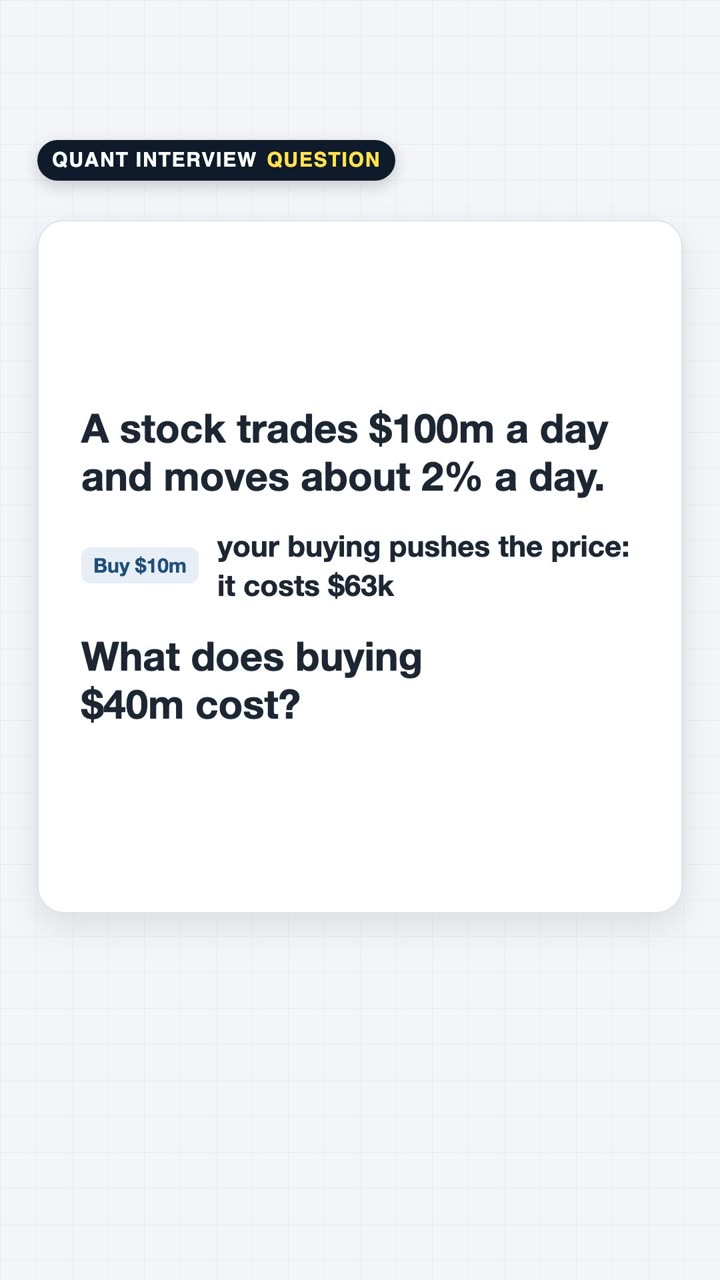
Impact in price terms scales with volatility and with the square root of the order size as a fraction of daily volume.
- Participation: your order as a fraction of daily volume.
- A constant of order one, estimated per market.
Why the exponent is a half. It is one of the most robust empirical regularities in market microstructure, observed across asset classes and decades, and its universality is more striking than any single derivation. The intuition most people carry is that the book refills as you trade, so each successive unit costs less than a linear model implies – and that latent liquidity, not the visible book, is what you are consuming. The practical point is that impact is concave: doubling your size less than doubles the cost per share, which is why large trades are possible at all, while total cost still grows faster than size.
Proposition 7.3
Capacity follows from impact
Total cost grows as – impact per share times shares – while gross alpha grows linearly in . The two curves cross, and where they cross is the capacity. Beyond it you are trading for the broker.
Holds when
- Capacity scales with liquidity, so the same signal carries far more in large caps than in small.
- A faster signal has lower capacity, because it must be traded more urgently and more often.
- Report capacity alongside Sharpe; a Sharpe of 2 on $20m is a different business from a Sharpe of 1 on $2bn.
The rest of this lesson is in Premium
You have read the opening. 12 more sections follow, including 5 worked examples and 3 quick checks.
Nothing is charged for 7 days, and you can cancel before then. Not ready for a trial? A free account, with no card, saves your progress and opens the free questions, the drills and a mock paper. Or read The law of large numbers and the central limit theorem in full, free.