Constructing a signal: standardisation, neutralisation and combination
SIG · Chapter 212 min readAsked at Two Sigma, AQR, Citadel, Point72
Assumes The research pipeline: from hypothesis to live capital.
 1:02
The lesson in a minutePremium
The key idea, drawn and talked through in a short video before you read. Lesson videos come with Premium.
Start the 7-day free trialUnlockAfter this lesson you should be able to
- Standardise a raw feature without leaking information.
- Neutralise a signal against known factors and say what remains.
- Combine several signals sensibly.
A raw feature is not a signal. Turning one into the other means putting it on a comparable scale across assets, removing the exposures you are not being paid for, and deciding how it combines with everything else you already trade – and each of those steps can destroy the signal if done carelessly.
Proposition 2.1
Standardise cross-sectionally
Convert the raw value to a z-score within each date, using only that date’s cross-section. That makes assets comparable, puts the signal on a scale you can size from, and – crucially – uses no information from any other date, so it cannot leak the future.
Holds when
- Winsorise or rank first: a single extreme value otherwise dominates the whole cross-section’s scale.
- Ranking is the most robust choice and discards magnitude, which is usually a reasonable price.
- Never standardise using full-sample statistics – that is look-ahead with no trace in the code.
Derivation 2.2
Neutralisation
Remove the part of the signal explained by exposures you do not want.
Regress the signal cross-sectionally on the factor exposures at each date.
Keep the residual – the part orthogonal to the factors.
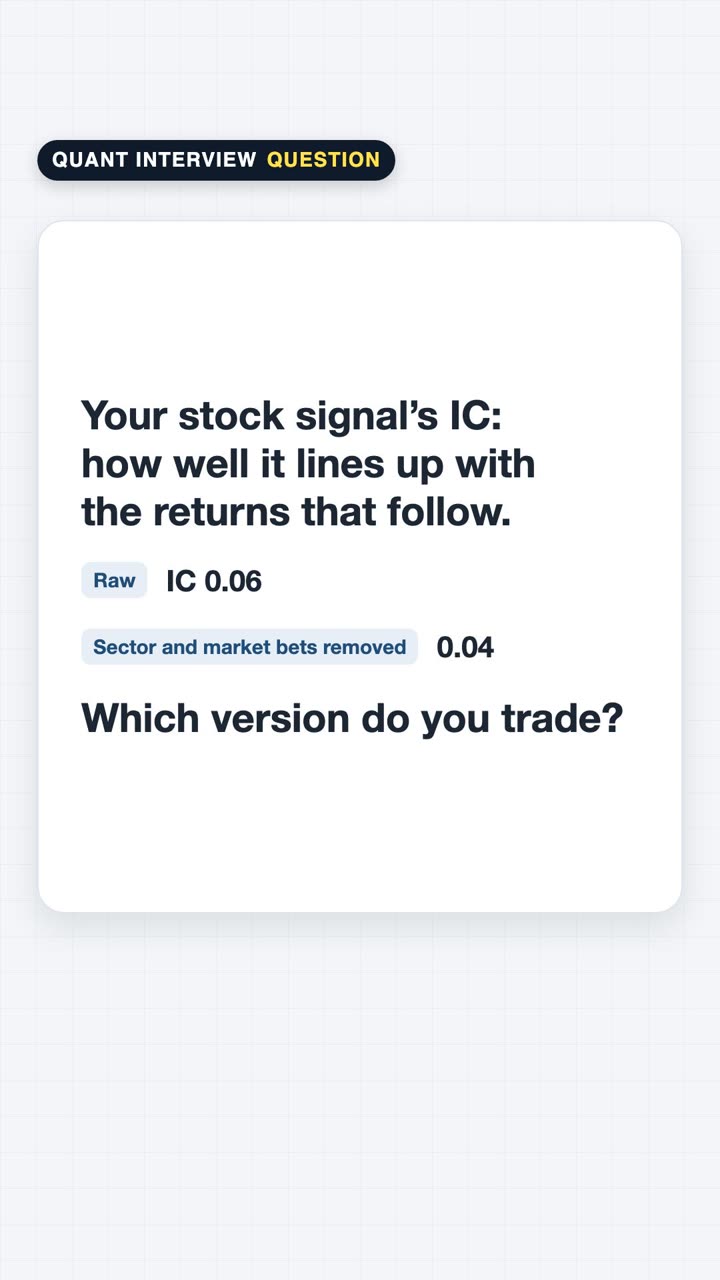
Why you give up return to neutralise. Neutralising almost always lowers the raw information coefficient, which looks like a loss and is usually a gain. The exposure you removed was paying you a factor premium you could have bought far more cheaply with an index – so you were not being paid for skill, and you were carrying a risk your risk model already charges you for. What remains is smaller and genuinely yours, and because it is uncorrelated with the factors it adds far more to a portfolio than its standalone IC suggests. This is the Frisch–Waugh–Lovell theorem doing portfolio work.
Example 2.3
A signal has an IC of 0.06 raw and 0.04 after neutralising against sector and beta. Which do you trade?
Show the worked solutionHide the worked solution
Worked solution
- Formula
- Substitute
- Solve
- Answer
Sanity check. If nearly all of the raw IC had vanished instead of two-thirds of it surviving – say 0.06 falling to 0.005 – the correct conclusion would be different: the signal was a factor bet, and there is no alpha to trade.
Proposition 2.4
Decay and smoothing
A signal computed each day is noisy, and trading it in full each day generates turnover that costs more than the noise is worth. Smoothing – an exponentially weighted average over a horizon matched to the signal’s half-life – keeps most of the information and cuts the turnover sharply.
Holds when
- Match the smoothing horizon to the IC decay curve, not to convenience.
- Over-smoothing delays the signal and costs real alpha, so it is a trade rather than a free improvement.
- A trading band – only rebalance when the target moves enough – is often better than smoothing the signal itself.
The rest of this lesson is in Premium
You have read the opening. 11 more sections follow, including 4 worked examples and 3 quick checks.
Nothing is charged for 7 days, and you can cancel before then. Not ready for a trial? A free account, with no card, saves your progress and opens the free questions, the drills and a mock paper. Or read The law of large numbers and the central limit theorem in full, free.