Delta hedging in practice: how often, and what it costs
GRK · Chapter 313 min readAsked at Optiver, SIG, IMC, Akuna
Assumes Second-order Greeks: gamma, vanna, volga and the shapes they take.
 0:59
The lesson in a minutePremium
The key idea, drawn and talked through in a short video before you read. Lesson videos come with Premium.
Start the 7-day free trialUnlockAfter this lesson you should be able to
- Say what a delta-hedged option position actually earns.
- Describe how hedging error behaves as rebalancing becomes less frequent.
- Trade off hedging error against transaction costs.
Black–Scholes assumes continuous costless hedging. Neither holds, and the gap is the whole of an options desk’s day-to-day P&L: you hedge discretely, which introduces error, and each hedge costs a spread, which means hedging more is not always better.
Equation 3.1
What a hedged position earns
Over a day, a delta-hedged long option earns the difference between the variance the stock delivered and the variance you paid for – weighted by dollar gamma.
- Dollar gamma, the sensitivity to squared percentage moves.
- The whole bet, in variance terms.
Proposition 3.2
The break-even move
Set the gamma term equal to the theta and solve: the position breaks even on a daily move of roughly – that is, on exactly the move the implied volatility was pricing. Move more and gamma wins; move less and theta does. This is the cleanest statement of what a long option position needs.
Holds when
- A 16% implied volatility needs about a 1% daily move to break even.
- The relation is about the size of the move, not its direction.
- It holds per rebalancing interval, so hedging twice a day changes the relevant .
Example 3.4
You are long a delta-hedged option with dollar gamma such that a 1% move earns $500 of gamma P&L. Implied volatility is 16% and the stock moves 1.5% today. What do you make?
Show the worked solutionHide the worked solution
Worked solution
- Formula
- Substitute
- Solve
- Answer
Sanity check. A move half as large again produces gamma P&L a bit over twice as big, because the payoff is quadratic. That convexity is exactly what you bought, and it is why a few large days dominate a long-gamma month.
Proposition 3.5
Hedging error from discreteness
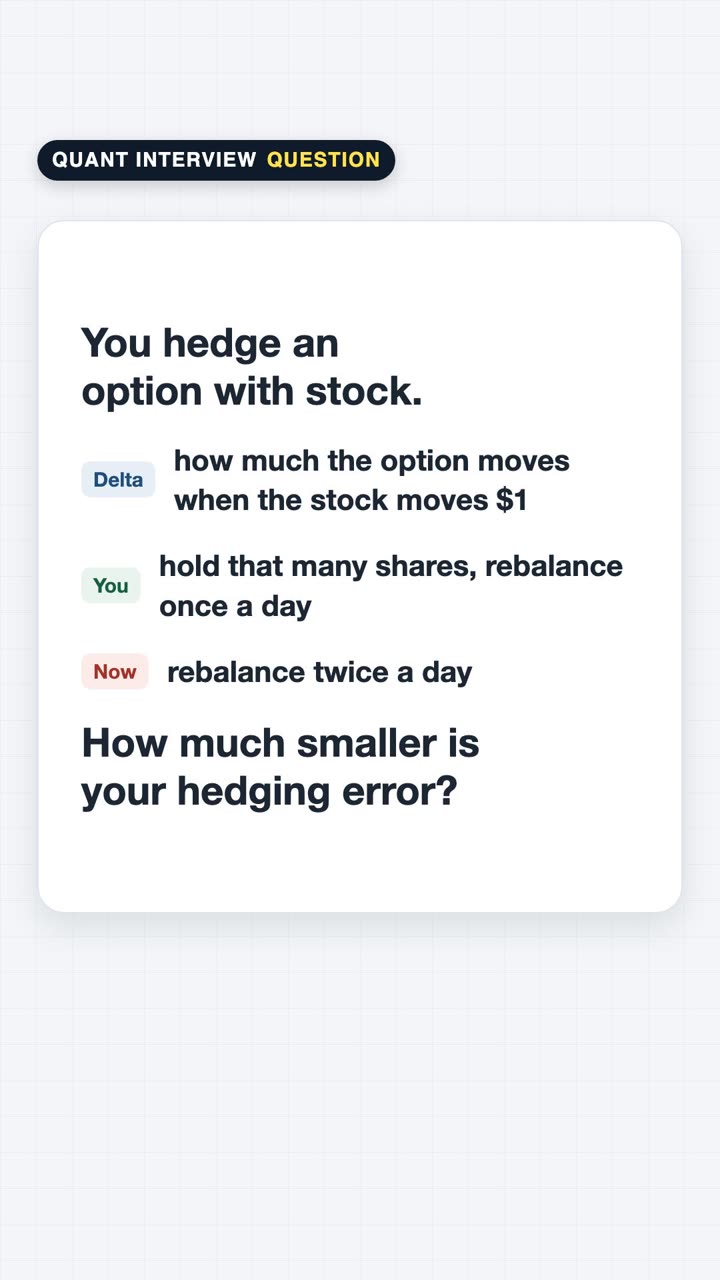
Hedging times over the life of the option leaves a random hedging error whose standard deviation falls as . It is mean-zero for a fairly priced option, so discrete hedging does not bias your P&L – it adds variance. The consequence is that a "hedged" position still has a distribution of outcomes, and a desk sizes for that rather than treating the hedge as exact.
Holds when
- Quadrupling the hedge frequency halves the error, and multiplies the transaction costs by four.
- Hedging on a fixed move rather than a fixed time is usually better, because it concentrates effort where gamma is being realised.
The rest of this lesson is in Premium
You have read the opening. 10 more sections follow, including 4 worked examples and 3 quick checks.
Nothing is charged for 7 days, and you can cancel before then. Not ready for a trial? A free account, with no card, saves your progress and opens the free questions, the drills and a mock paper. Or read Forwards, futures and the cost of carry in full, free.