Market-data cases: short-horizon prediction from the order book
CASE · Chapter 412 min readAsked at Citadel Securities, Two Sigma, Jump, Optiver
Assumes Causal cases: treatment effects, confounding and surprising results.
 0:56
The lesson in a minutePremium
The key idea, drawn and talked through in a short video before you read. Lesson videos come with Premium.
Start the 7-day free trialUnlockAfter this lesson you should be able to
- Build the standard order-book features and say what each measures.
- Choose a sensible target for a short-horizon predictor.
- Identify the microstructure traps that manufacture fake signal.
Short-horizon prediction is the case a market-making firm will hand you, and it is unusual in having plenty of data and a genuinely detectable signal. What it lacks is any tolerance for sloppiness about timestamps: at this frequency, a millisecond of misalignment is the difference between a real feature and a perfect one.
Proposition 4.1
Choosing the target
Predict the change in the mid or, better, in the microprice, over a horizon matched to how long you can act. Predicting the traded price mixes in which side traded, and predicting the return over a horizon shorter than your latency describes something you cannot capture.
Holds when
- Use the microprice as both feature and target: the mid is a stale reference when the book is lopsided.
- Horizons from a few hundred milliseconds to a few minutes are the usual range.
- Defining the target in ticks rather than per cent avoids scale problems across names.
| Feature | Definition | What it captures |
|---|---|---|
| Book imbalance | Pressure from resting size – the strongest single feature | |
| Microprice | Size-weighted fair value | |
| Trade imbalance | Signed volume over a window | Realised aggression |
| Spread | Uncertainty and liquidity | |
| Depth slope | How quickly size builds away from the touch | Resilience to a large order |
| Queue position | Volume ahead of your order | Your probability of being filled |
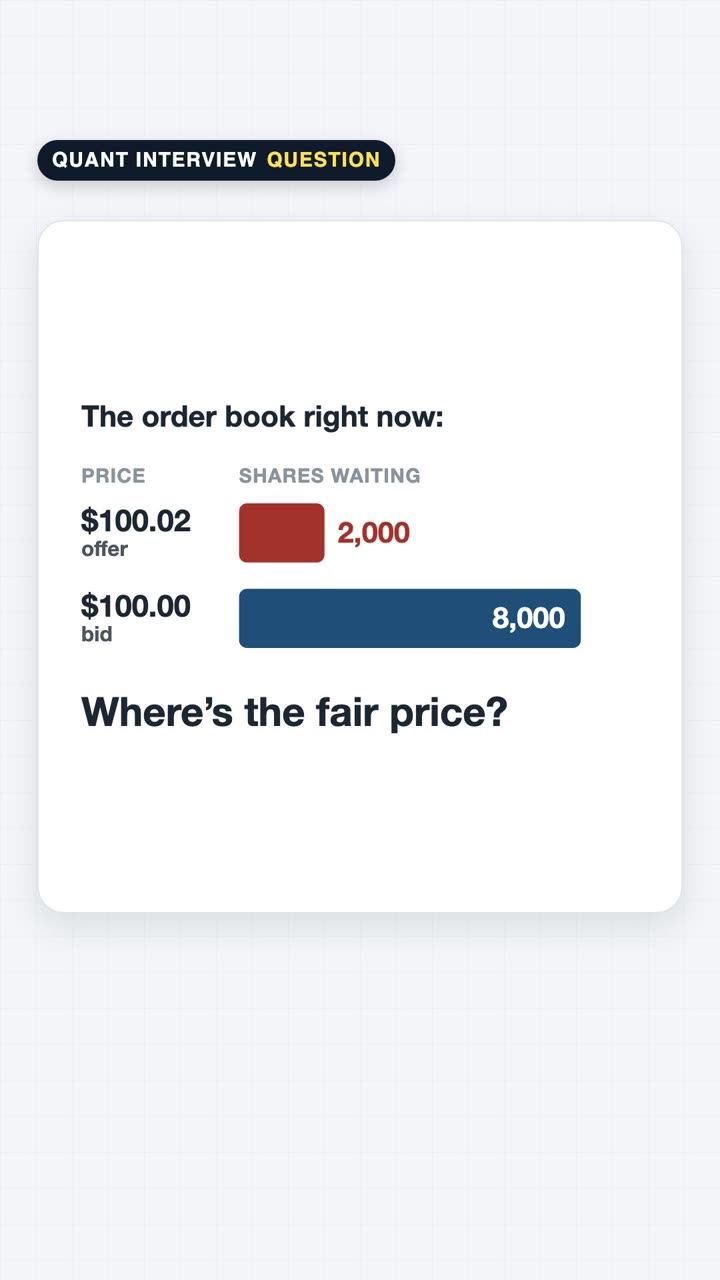
Why the microprice beats the mid. The mid weights both sides equally, and a book with a thousand lots bid against a hundred offered is not balanced – the queue of buyers has to work through a thin offer, so the next trade is more likely to be up. Weighting each price by the size on the opposite side captures that: heavy bid size pulls the fair value toward the offer. It is a one-line change that improves almost every downstream calculation, and quoting symmetrically around the mid in a lopsided book is a reliable way to be adversely selected.
The rest of this lesson is in Premium
You have read the opening. 11 more sections follow, including 4 worked examples and 3 quick checks.
Nothing is charged for 7 days, and you can cancel before then. Not ready for a trial? A free account, with no card, saves your progress and opens the free questions, the drills and a mock paper. Or read The law of large numbers and the central limit theorem in full, free.